How Many Times Can You Refinance a House in Seattle?
Read more


Low down payment and low rate home loan options for Seattle
Monday - Sunday | 8:00 am - 8:00 pm
We will never rent, sell, or misuse your data, ever.
A Division of City Mortgage Brokers, LLC
MB#2158059

This article was originally published on September 15, 2019. It was updated on October 15, 2026.
If you’re a few months, or even a few years, into a 30-year mortgage on your Seattle home, the mortgage payoff date can feel so far away it’s hard to picture.
And there’s a reason for that.
Early on, most of your monthly mortgage payment goes to interest, so your balance barely moves.
For example, if you recently bought a home in Seattle this past summer, which on average retails for roughly $850,000, with 20% down, you would owe $680,000 on that loan. At today’s average rate of 7.40%, about $4,193 of your monthly payment goes to interest.
Which means only about $515 goes toward what you owe.
But the truth is, you don’t have to stay on that interest-heavy path for 30 years.
Paying off your mortgage early is doable, and it doesn’t take a big budget or a complete 180-degree pivot in how you handle your mortgage.
In this guide, we’ll walk through three simple ways to pay off your mortgage faster. They range from small habits you can start this month to completely new strategies for approaching your mortgage.
There’s even an extra special bonus strategy that can cut close to a decade off your loan.
But we’re saving that one for the end.

Remember that first payment where only about $515 went toward your balance?
On a 30-year schedule, it can take more than 20 years before most of your payment flips from interest-forward payments to principal ones. But shortening your loan can speed that up, and typically you’ll see the benefits in three places.
First, there’s interest.
It’s charged on whatever you still owe, so every year you cut off your loan is a year of interest you never pay. On that $680,000 home loan at 7.40%, you would likely pay about $1.01 million in interest over 30 years, assuming a fixed-rate mortgage.
Which is way more than you borrowed in the first place.
But if you pay it off in 20 years instead of 30 (which takes a bigger monthly payment), the total interest drops to about $625,000.
Leaving roughly $390,000 in your pocket.
Next up is equity.
That’s the part of your home you own outright, and it’s what you walk away with when you sell. After five years on a 30-year loan, you would have probably paid down only about $37,000, even after sending the bank more than $280,000.
On a 20-year schedule, it’s closer to $90,000.
Last but not least, there’s retirement. If you were to take out a 30-year loan at 40, your last payment lands at 70. Cut 10 years off, and you’re done at 60.
Starting to see a pattern?
Now, let’s dive into the strategies that can help you keep more of that interest in your pocket, starting with the easiest one.
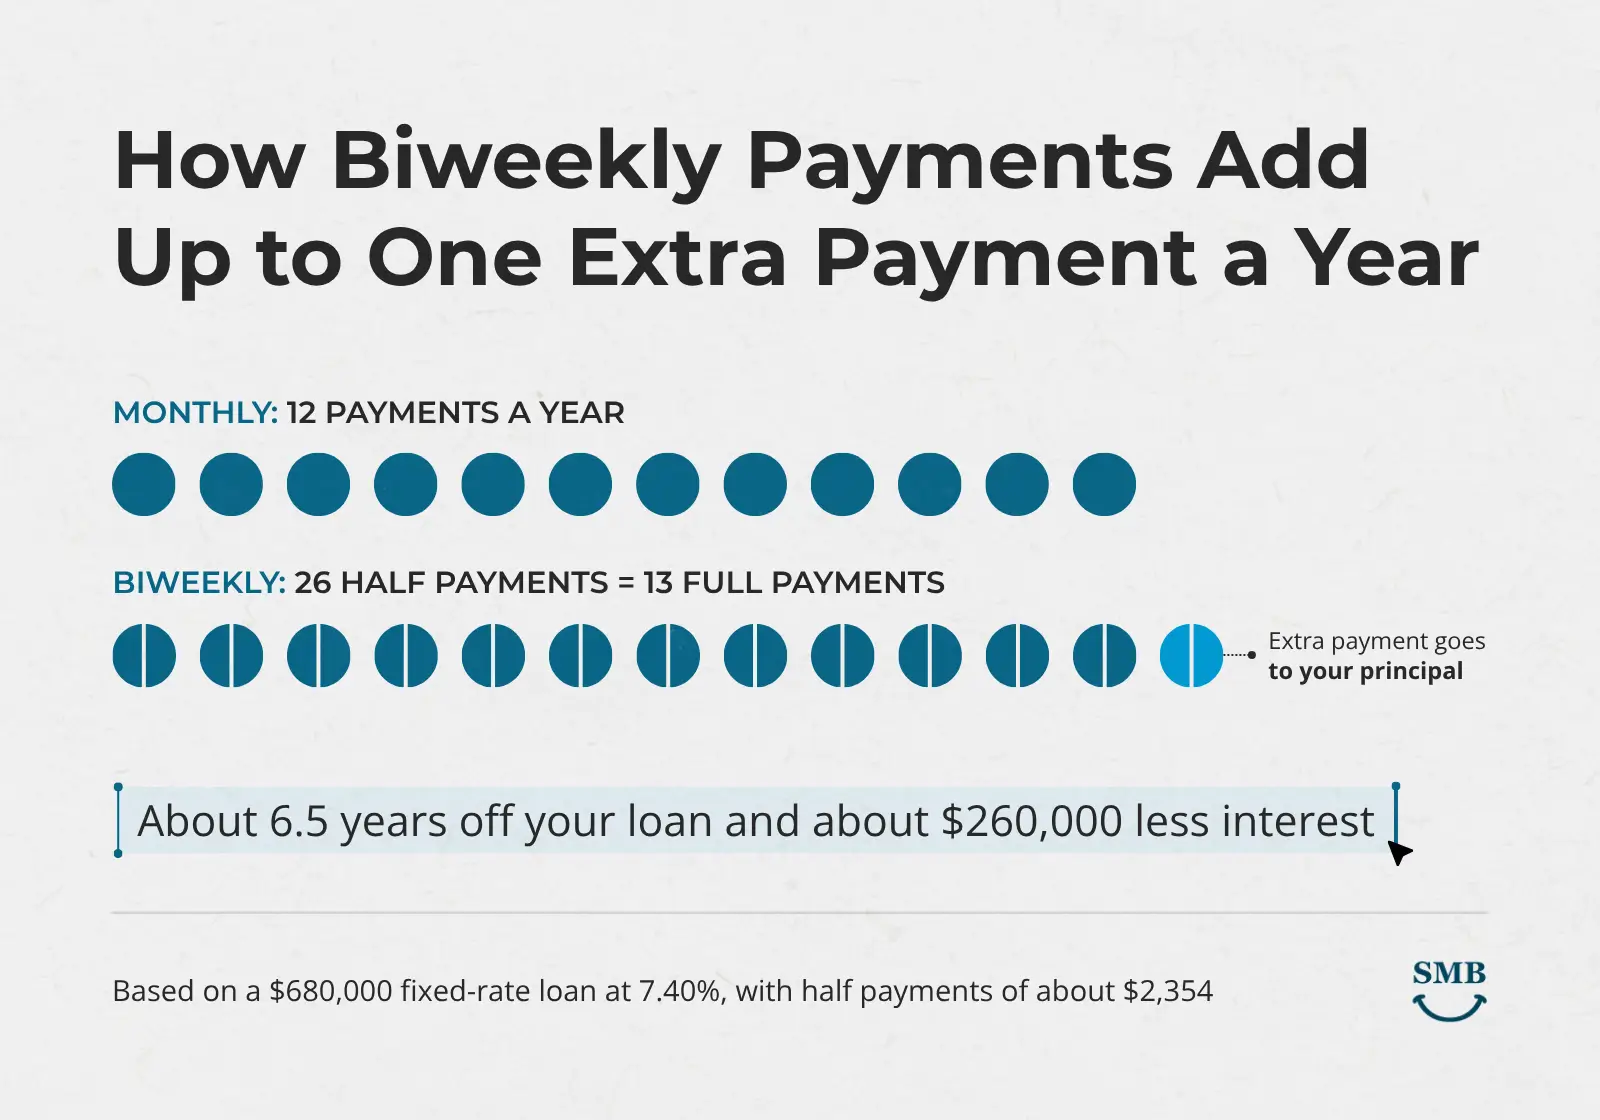
More often than not, mortgages are set up for one payment a month, which works out to 12 mortgage payments a year. But a biweekly plan splits that payment in half and has you pay the half every two weeks.
At first glance, it looks like the same amount of money.
But a year has 52 weeks, which means 26 half payments. That’s 13 full payments instead of 12, so you make one extra monthly payment a year without saving up a big chunk of cash.
That extra payment goes toward your mortgage principal, the amount you borrowed. And since interest is charged on whatever you still owe, a lower balance means less interest every month after.
If we revisit that $680,000 loan at 7.40%, half the monthly payment comes in at about $2,354. Paid every two weeks, that one extra payment a year would cut roughly six and a half years off the loan and save about $260,000 in interest over the life of the loan.
Not bad, right?
Plus, it makes sense if you’re paid every other week.
If biweekly payments don’t line up with your paychecks, you can get a similar result by adding a little extra to your payment each month.
If you were to add just $200 to your regular payment, that extra increase could skip interest and go straight to your balance. And since interest is charged on what you still owe, next month’s interest charge will end up a bit smaller. So by default, a little more of your regular payment pays down your principal faster too.
When you apply a small shift like that and repeat it every month, the savings compound over the long run.
Let’s do the math.
On that same $680,000 loan at 7.40%, an extra $200 a month would cut nearly four years off your loan and save about $157,000 in interest.
Bump your monthly contribution to $500, and you would be done almost eight years early, with about $309,000 saved.
You also don’t have to pick a number and stick with it forever. You can start with what fits your budget now, then raise it when you get a raise or pay off other debt, like car or personal loans, for example.
There is one thing to check first, though. When, and if, you send extra money, mark it as “principal only.” Otherwise, your servicer may hold it and apply it to next month’s payment, which won’t lower your principal balance any faster.
Not every extra dollar shows up on a schedule. Some of it lands all at once, like a work bonus, a tax refund, or a cash gift from family.
When that happens, you can send some or all of it straight to your principal. A lump sum works the same way as the extra $200 a month example we spoke about in the last strategy. It lowers what you owe, so every interest charge after that is based on a smaller balance.
It just does it in one shot.
Let’s go back to that $680,000 loan at 7.40%.
If you put a one-time $10,000 bonus toward principal at the end of your first year, you would cut about 17 months off your loan. You’d also save roughly $71,000 in interest.
That’s just from a single payment.
Now say you sent $5,000 every year, maybe from a tax refund you can expect to receive. That would take about six years and eight months off your loan and save around $263,000.
Before you send any lump sum payment, call your servicer and ask them to apply it as “principal only,” then check that it shows up on your next statement.
And don’t drain your savings to do it. Because once that money is in your house, it’s hard to get it back if you need it elsewhere.
Every strategy so far asks you to find extra money, whether it’s a bigger payment, a bonus, or a tax refund.
The bonus strategy we promised at the start doesn’t.
It shortens your loan at the payment you already have.
It’s called Step Down Refinancing, and it’s a program we built at Seattle’s Mortgage Broker to get you a lower interest rate whenever the market allows.
Most homeowners who refinance add thousands in loan costs onto their balance. But our Step Down Refinancing program keeps your Total Loan Costs at zero. The lender pays us directly, and part of that covers your costs.
Anything we can’t zero out, we refund at closing.
Each time interest rates drop, you keep your payment the same and cut the time left on your loan.
One of our clients stepped down six months after buying his new home. His first Step Down refinance moved him into a shorter-term mortgage, from 29 and a half years left to 20, at the same payment.
That’s more than any options we mentioned earlier.
You don’t have to use every strategy at once. Start with the one you can afford, then add another when you can.
If you’re paid every other week, biweekly payments are an easy first step. If you’d rather set your own pace, extra mortgage payments of $200 or $500 a month work too. And when a bonus or tax refund lands, sending part of it to principal can cut months off your loan in one shot.
These also work together. You could switch to biweekly payments now and put next year’s tax refund toward your balance.
Step Down Refinancing is the only strategy here that doesn’t ask you to find extra money. Your payment stays the same, your rate drops when the market allows, and the time left on your loan gets shorter. Because your Total Loan Costs stay at zero, you aren’t stacking thousands onto your balance each time.
Want to see how Step Down Refinancing could work on your loan? Reach out to our team at Seattle’s Mortgage Broker for a refinance quote.
Joe Tafolla is the founder and lead mortgage broker at Seattle’s Mortgage Broker, a full-service mortgage consulting firm dedicated to helping homebuyers secure financing with competitive rates, faster closings, and personalized service.
With more than two decades in the mortgage industry, Joe has helped hundreds of families achieve homeownership.