

5 Tips To Secure A Cash-Out Refinance That Improves Your Financial Future
Read more


Low down payment and low rate home loan options for Seattle
Monday - Sunday | 8:00 am - 8:00 pm
We will never rent, sell, or misuse your data, ever.
A Division of City Mortgage Brokers, LLC
MB#2158059
If you bought a home in Seattle in the last few years, there’s a good chance your mortgage rate is higher than you would like.
When interest rates started climbing in 2022, a lot of buyers went ahead and bought anyway. The plan was to buy now and refinance later, once rates came back down. In the mortgage world, that’s known as “marry the house, date the rate.”
To be fair, rates did come down.
Just not nearly as low, or as fast, as many people hoped. Instead of one big drop, mortgage rates have tiptoed downward in smaller, less predictable steps.
That’s left homeowners who’ve already refinanced their original mortgage asking the same questions.
Can I refinance again? And if so, again after that?
The short answer is yes. There’s no set-in-stone cap, guideline, or rule you need to follow. You can refinance your home as many times as it makes sense for you.
The real question is whether each mortgage refinance is worth it once you factor in the closing costs that come with it. Those upfront costs are the reason so many homeowners sit and wait for the “big drop” that only comes around once in a blue moon.
But there is a way around it.
A way that doesn’t handcuff you to the old “save 1% first” strategy many of us have followed for years.
But before we share how it works, let’s look at why so many homeowners end up waiting in the first place.
Picture a Seattle homeowner who refinances their existing mortgage to take advantage of lower interest rates.
On paper, it’s a win across the board. Their monthly mortgage payments drop, and they’ve freed up thousands of dollars in financial wiggle room over the course of a year.
Sounds great, right?
But things feel a lot less exciting once it’s time to look at the final number on Line D of their Closing Disclosure or Loan Estimate.
Every refinance comes with a stack of fees for setting up the new home loan:
And that’s just to name a few.
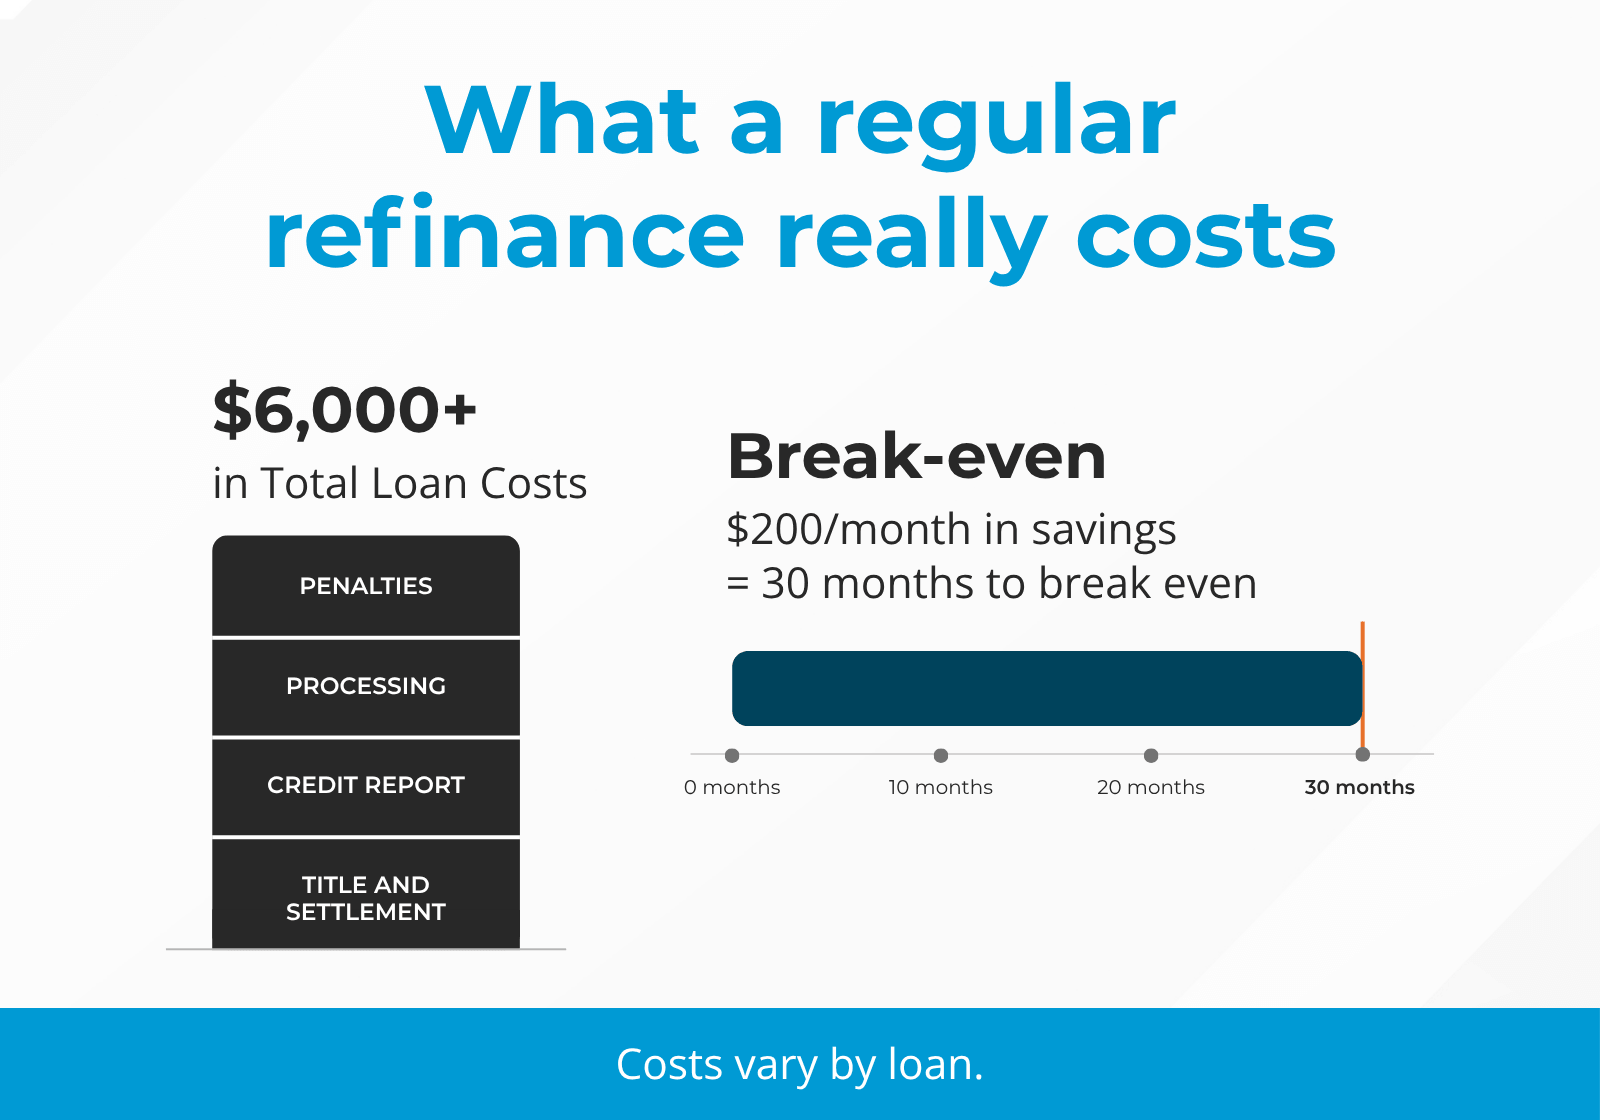
When you tally up all of those refinancing costs in a market like Seattle, they can often exceed $6,000!
If you pay closing costs out of pocket, that money is gone on day one. If you roll them into your new loan, your loan amount goes up by the same amount.
Either way, before the refinance even has a chance to come out ahead, your monthly savings have to earn back that $6,000.
Say, for example, the new rate lowers your mortgage payment by $200 a month. That would mean it takes 30 months, or two and a half years, just to break even.
This cost is also where the old “save 1% first” rule comes from.
You know, the one your friends, neighbors, and parents are always preaching.
“Don’t refinance unless you can drop your rate by at least one percentage point.”
But if we’re being honest, that rule traces back to a single source: lenders who charged heavy origination fees. Those lenders typically took around 3% or more.
On a large loan, that could mean $20,000 in fees. So yes, with costs that high, you would definitely need a full 1% drop to make the math work.
Now back to the recently disappointed homeowner we mentioned earlier.
While they’ve accepted the reality of waiting long enough to break even, rates keep moving.
A small dip comes along. Then another. Each one could lower their rate a little, but none is big enough to justify adding another $6,000 to their mortgage balance.
So they pass and keep paying interest at the higher rate.
When you zoom out, the thing clearly holding these homeowners back is the cost of each refinance. Take that cost away, and the math looks very different.
In the last section, we looked at the $6,000 reason that keeps homeowners from even thinking about a refinance.
Now let’s take those loan costs out of the picture.
Say that same homeowner could refinance without adding a dollar of loan costs to their loan principal.
There’s no $6,000 to earn back and no 30-month wait to break even.
That leaves just one question: does the new rate lower your interest costs? If it does, the refinance is worth taking.
You’ll still want the savings to be worth your time. But without loan costs, the bar drops from a full percentage point to almost any meaningful dip.
Say a small dip saves you $75 a month. With nothing to earn back, that’s $900 in your pocket over the first year.
And you don’t have to stop there.
When interest rates drop again, you can refinance again and add a little more savings on top of what you already have.
Think of it like chopping down a tree. One perfectly timed swing won’t bring it down, but steady swings will, and each one gets you closer.
Your mortgage rate works the same way. If you hold out for one big drop, you pay the higher rate the whole time you wait. That extra interest adds to the total interest you pay over the life of your loan, and it’s gone for good. If you take the smaller drops as they come, your rate comes down one step at a time.
So, how do you take loan costs off the table?
That’s where Step Down Refinancing comes in.
Step Down Refinancing is a program from Seattle’s Mortgage Broker designed to help homeowners get past the hurdles that come with refinancing.
It lets you lower your mortgage rate in small steps as rates drop, without adding loan costs to your balance each time.
As you know, every refinance comes with fees for setting up the new loan, such as the appraisal, processing, credit report, and title and settlement fees. These are listed on a form called the Closing Disclosure, which you get before you sign. Line D on that form adds them all up and is labeled Total Loan Costs.
Normally, you either pay that amount out of pocket or add it to your new loan.
Step Down Refinancing takes that cost off your plate.
When you refinance with us, we match you with a lender that fits your financial situation. That lender pays us a commission directly for bringing them your loan, and we use part of that commission to pay your Total Loan Costs. From there, we zero out every fee we can, and anything left over gets refunded to you at closing.
Once you’re ready to move forward, you have two options. You can lock your rate now and secure a set amount of savings. If rates keep falling before you close, we can move your loan to a new lender, so you’re not stuck with the same lender at a higher rate.
Or you can float.
You finish the paperwork with us but wait to lock your rate until the very end. When the market offers favorable refinancing terms you’re happy with, you lock and close a few days later.
The refinancing process moves fast. But by law, we can’t close a primary residence in under two weeks. But we can usually get your paperwork done in under a week, so you can kick back while the clock runs out.
There’s one thing you’ll still bring to closing: money to fund your new escrow account. Your current escrow account can’t transfer to the new loan, so it has to be funded fresh.
That’s why we time most closings for the very end or very beginning of the month. The amount you bring in is usually close to one mortgage payment, and your next payment isn’t due for about 30 days. That way, you don’t pay twice in one month. Whatever is left in your old escrow account gets refunded to you. Many clients put that refund toward their loan principal, but it’s yours to use however you like.
The end result is a lower rate, with none of those pesky fees stacked on top of it. Then the cycle repeats. Each step down replaces your old mortgage with a new one at a lower rate.
After six on-time payments, you can step down again. That six-month waiting period gives rates time to move enough to make the next step worth your while. Each time rates dip, we run the same refinancing process, and your rate comes down another step.
There’s no limit on how many times you can do it.
Lower monthly payments aren’t the only way to use Step Down Refinancing.
If your payment already fits your budget, you can keep it the same and shorten your loan term instead. Your rate goes down, your payment stays put, and the time left on your loan shrinks. That means you can pay off your loan early without higher monthly payments.
One of our clients did a purchase and two refinances with us in about 18 months. They kept their payment the same each time. Together, those steps cut 11 and a half years off their mortgage term.
Paying off your loan sooner can lead to significant savings. For this client, it added up to over half a million dollars.
Some homeowners use Step Down Refinancing to remove a co-signer from their current loan, such as after a divorce or once a family member who helped them buy no longer needs to be on it.
A refinance is usually the way to do that, and it normally costs thousands. With Step Down Refinancing, you can put the loan in your name alone without paying those Total Loan Costs, even if your rate stays about the same.
When mortgage rates dip, it’s natural to wonder if another refinance is worth it, or if you would just be piling more costs onto your loan to save a few dollars a month.
That hesitation makes sense when every refinance comes with thousands in loan costs.
But once those costs are covered, the math gets a lot simpler. Every time you refinance a mortgage, the question is the same: does the new rate lower your interest? If it does, it’s worth taking. And with Step Down Refinancing, once you’ve made six on-time payments, you can take the next one, too.
So how often you refinance just depends on how often rates give you the chance.
If you expect rates to keep drifting down, there’s no need to sit on a higher rate waiting for the perfect drop. Get a refinance quote from Seattle’s Mortgage Broker, and we’ll show you how Step Down Refinancing could work for your loan and what your potential savings could look like.
Joe Tafolla is the founder and lead mortgage broker at Seattle’s Mortgage Broker, a full-service mortgage consulting firm dedicated to helping homebuyers secure financing with competitive rates, faster closings, and personalized service.
With more than two decades in the mortgage industry, Joe has helped hundreds of families achieve homeownership.