

How to Use Restricted Stock Units to Buy a Home in Seattle
Read more


Low down payment and low rate home loan options for Seattle
Monday - Sunday | 8:00 am - 8:00 pm
We will never rent, sell, or misuse your data, ever.
A Division of City Mortgage Brokers, LLC
MB#2158059
Scroll long enough, and every mortgage ad in Seattle starts to look the same. That trains you to compare Seattle mortgage brokers based on whoever posted the lowest figure that morning.
But the rate isn't what closes your home loan.
A person is.
And that person, not the number, decides whether this works out.
Rates fluctuate daily, and the one in the ad may have been priced for someone who shares nothing with you but a zip code.
They tell you nothing about whether your file clears underwriting, whether you sign on the date written into your contract, or whether anyone picks up the phone in year three of your loan term.
The person running your file decides all of that, and there are four things worth knowing about how they operate before you hand them the responsibility of managing your biggest purchase.
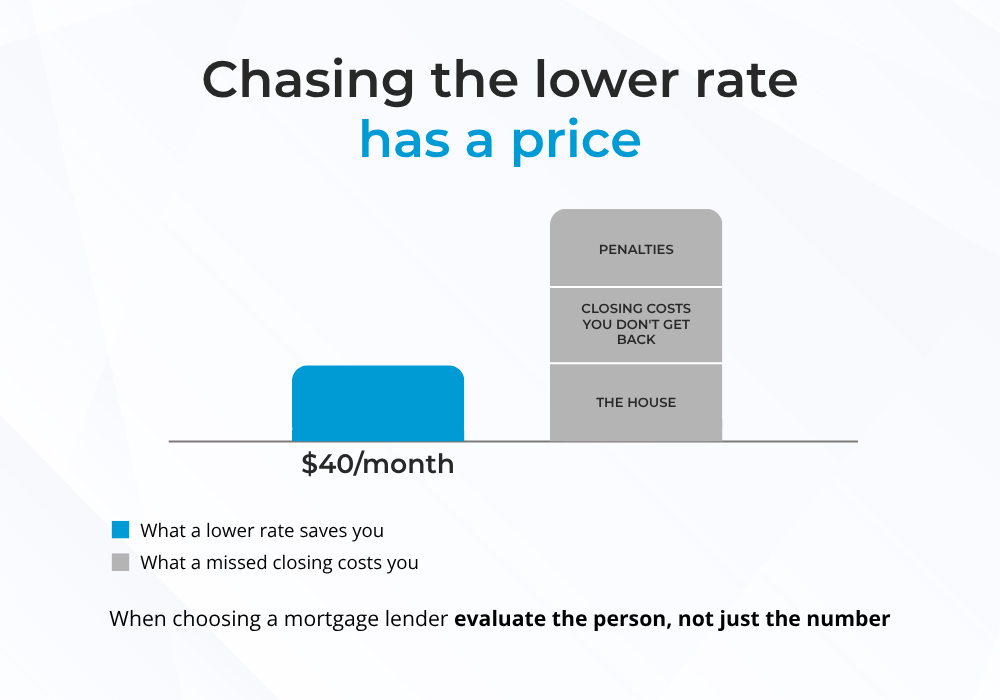
A lower rate can trim forty dollars off your monthly payments. And yes, over years that can feel like real money, which is why people pick a lender on that number alone.
But picture this scenario.
You're under contract. You've sent every document the seller has asked for. Then two weeks go by, and you assume things are moving.
Unfortunately, that silence often means nobody has opened your file.
So the problems that will stall your loan sit there unread: a gap in your work history, something on your credit nobody flagged, a large deposit nobody can trace to a source, or a property issue like a building whose finances don't meet the mortgage lender's guidelines.
An experienced loan officer catches all of those in the first conversation because they know where loans get stuck.
But with an inexperienced loan officer, those issues arrive one at a time, after the inspection, after the appraisal, after you've handed over the good-faith deposit you can lose if the deal falls apart. Then your lender asks for more time, and you're negotiating for a house you thought was yours.
So naturally, it’s important to weigh that forty dollars against your deposit, the closing costs you won't get back, and of course, the house.
Mortgage rates come from the bond market, which means every lender in Seattle is working from roughly the same pricing each morning.
With that said, the differences between their quotes are small, and they’ll move again tomorrow.
What doesn't change is the person who's responsible for getting your loan through underwriting and to the closing table before your contract expires. That part of the mortgage process is worth vetting, and you can do it in one conversation if you know what to listen for.
Here are four things to think about, roughly in order of importance.
It may come as a surprise, but a mortgage license only takes a few weeks to earn, which means the pool of licensed professionals includes plenty of people who have never worked a difficult file. On the other hand, learning where loans get stuck takes years, and that difference becomes abundantly clear at the worst possible time for buyers.
For example, a newer loan officer can quote your rate correctly and still miss what underwriting will question later, like how your personal income is structured, or a property the lender has continuously refused to approve.
So it's worth asking a few questions before you commit, such as: how long have they been originating loans? How many files like yours did they close last year? And what do they foresee being an issue with yours?
Reviews are written about companies, but loans are handled by individuals, so find out who will be running yours and search for that person by name.
Google reviews are the most useful ones because they're attached to real closings and come from clients who had money on the line.
Read for whether past customers closed when they expected to and whether they could reach someone with a question, since those two failures are what cost buyers money.
But if you have a real estate agent you trust, ask them which lenders never give them trouble.
Your purchase contract has a closing date written into it, and unlike the interest rate, that date is not a preference.
If your lender misses it, you’re asking the seller for more time you have no real leverage to request, with your deposit already sitting in escrow and possibly another buyer waiting behind you.
So ask for numbers rather than reassurance, including how long the home loan process usually takes from application to closing. How often do they close on the assigned contract date? And what caused it the last time they didn't?
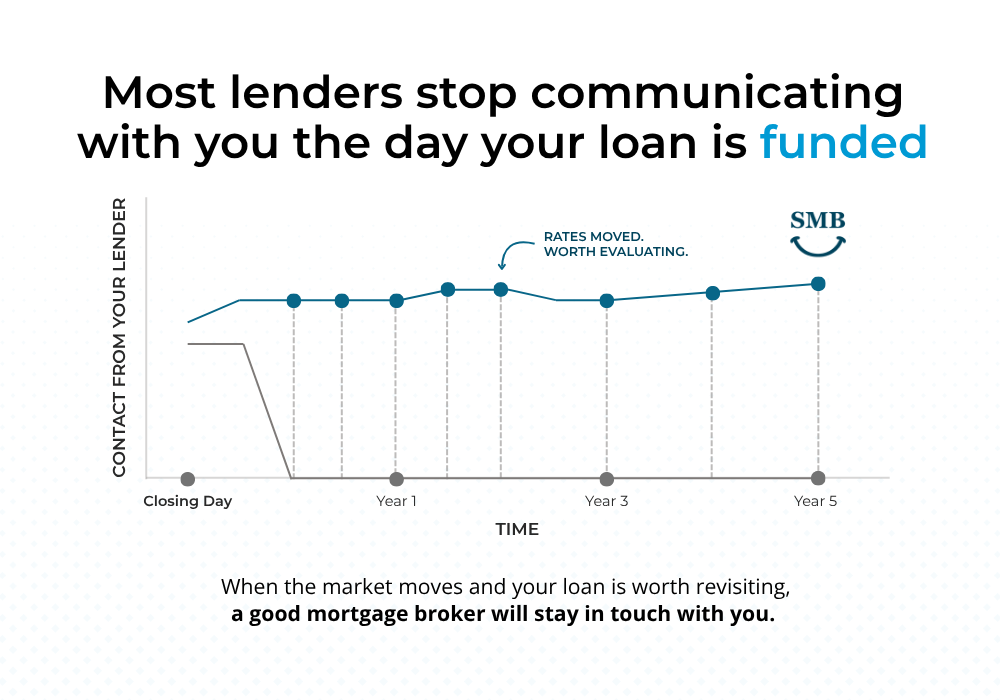
Most lenders go quiet once your loan is funded. You'll get a notice telling you where to send payments, and that's the last you hear from them, even as rates move and your loan becomes worth revisiting. Very few stay in touch and call you when it's worth acting on.
So it helps to know which kind of loan officer you're hiring before you sign. One who saves you money on this mortgage, or one who keeps saving you money for years after it closes.
In competitive housing markets like Seattle, the offers that win are the ones with no conditions attached.
So if your next purchase depends on selling the home you're in now, sellers read that as a risk they don't have to take, and when they're weighing multiple offers, yours gets passed over even when the money is right there.
That's a hard place to be, and it has nothing to do with how qualified you are. Plenty of well-qualified families lose the Seattle home they wanted for no other reason.
At Seattle's Mortgage Broker, we created our Contingency Buster Program to take on that part of the buying process.
Instead of asking a seller to wait and see whether your house sells, the program lines up a guaranteed backup purchase contract on your current home first, so a committed buyer is already in place. Your next offer goes in clean, with nothing riding on a sale that hasn't happened yet.
That changes three things for you.
First, you compete like a cash buyer. With no sell-first condition in your offer, a seller has no reason to choose someone else over you, and the loan can close in as little as 10 days.
Second, you move once. You buy your next home and settle in first, then sell your current house vacant and staged, which is how it earns full value.
And third, your current home is already covered. The backup purchase contract puts a committed buyer in place before you write your offer, so nothing is left hanging.
You shouldn't have to choose between selling first and losing the house you want. That's exactly what the Contingency Buster is built to solve. See how it could help with your next home purchase.
The rate you were quoted this morning is already gone. But the person handling your Seattle mortgage will still be there on closing day.
So evaluate the person first and the rate second.
One conversation is usually enough to make an informed call. If you ask the questions above, someone with years of files behind them will answer with depth and clarity. Someone without that experience will likely steer you back to the rate.
At Seattle's Mortgage Broker, we've spent decades structuring loans for buyers in Seattle, WA and across Washington. We regularly close in under two weeks. And we don't disappear once your loan funds, because when the market moves and your loan is worth revisiting, we're the ones who call you.
Speak with us to learn more about how we can help you secure your next home at the right rate.
Joe Tafolla is the founder and lead mortgage broker at Seattle’s Mortgage Broker, a full-service mortgage consulting firm dedicated to helping homebuyers secure financing with competitive rates, faster closings, and personalized service.
With more than two decades in the mortgage industry, Joe has helped hundreds of families achieve homeownership.